Who Gets Paid for a Consigned Coat
A consignment tag describes a possible sale, not an amount already owed to the person who brought the coat in. A short example shows how the settlement changes.
In this story 4 sections
A smart winter coat spends more time at a secondhand shop than either of the people who eventually meet over it. Its former wearer leaves it one afternoon. Its buyer arrives weeks later in weather cold enough to make the lining important. In between, the coat is measured, perhaps photographed, moved along the rack and offered for a price that can change. The person who brought it in may receive something from the sale. They have not ordinarily sold the coat to the shop at the start if the arrangement is consignment.
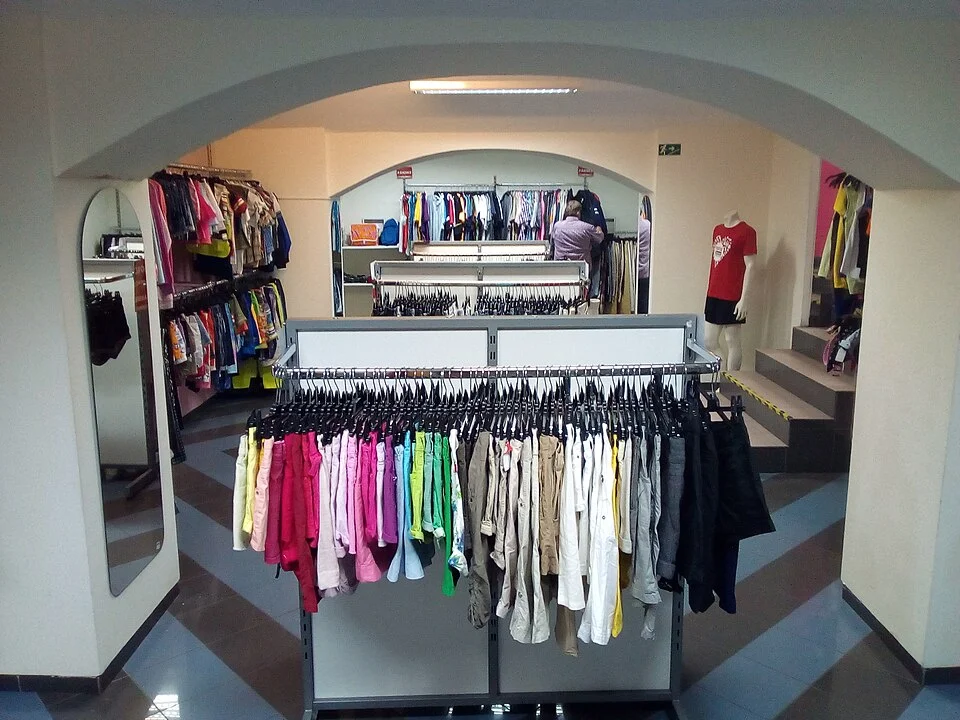
That difference can be hard to see from a row of used clothes. Some businesses buy the items they expect to resell. Some take them on consignment and share the proceeds when they sell, under terms set with the consignor. Others accept donations or combine more than one approach. The photograph here shows a shop that sells secondhand clothing. Its appearance alone cannot tell you how any particular item was obtained. For an economic account you need the kind of agreement one person had when they put the coat in another person’s hands.
There are three prices someone might mean
First consider the price attached to the coat when it goes on display. That is a proposed price for the next wearer. It may be changed under the arrangement or never result in a sale. Second, there is the price the buyer pays when a sale actually happens. Third, there is the amount owed to the consignor under the agreement. A percentage in a statement ordinarily has to be applied to some base, which could differ depending on the terms. It is unwise to take a share of the opening tag and record it as money already earned.
For a fictional example, suppose the opening tag says $80 and the agreement gives the person who left it 45 percent of the realized selling price, with no deductions for purposes of the example. At the original tag the payment would be $36. If an agreed markdown brings the price to $60 before someone buys it, the payment would be $27. The difference is $9, produced without changing the percentage. The shop’s share of that sale price would be $33, before the costs the shop still has to pay. Neither share says what the coat cost when it was bought new.
A useful comparison puts the consignor’s terms beside the shop’s pricing policy. Compare two fictional offers, one with a larger share of the sale and another that changes the price later or sets a different opening price. The number written as a percentage might favor the first. The expected payment depends on the likely selling price and whether the sale happens at all within the time available. A $90 opening tag with a 50 percent share could result in $30 if the item sells after it was marked down to $60. A $75 sale elsewhere at a 45 percent share would leave $33.75. There is no need for either shop to do anything unexpected for the smaller share to produce the higher payment.
The time until sale belongs to the deal
The person who no longer needs the coat can have a good reason to prefer quick payment. An outright buyer can offer an immediate price subject to its own checks. It can be less than the amount hoped for under consignment because the buyer is taking the chance that the coat will not resell at the desired price or time. A consignor who has no deadline to clear an item might willingly bear some of that uncertainty. Ask what happens to an unsold item if that uncertainty matters. Getting the coat back may be useful but also involve a return trip, or the agreement may offer a different outcome under stated terms.
The season can change the answer before either person expects it. A heavy piece placed on a rack just before warm weather might be hard to judge as a sale candidate, even if the store knows it would suit many people. Waiting to offer it can improve the alignment with buyers while delaying any payment and occupying space. Some shops describe season, condition and market demand in their acceptance instructions. They know that the same coat at the same time of year will be competing for space with many other pieces. The assessment can be similar to an ordinary appraisal while involving a quite distinct question about time.
Dates now enter more than one line on the record. There is the date the shop accepted the item and the time after which its terms allow something to change. There is the date of sale and the day by which the payment is ordinarily available. If the store has a collection window for unsold stock, that date belongs somewhere members of staff and the consignor can find. Discuss the relevant dates at the start. A coat that spent weeks on a rack will not become easier to match to a promised amount simply because one date was printed at the bottom of the ticket.
The shop supplies more than space on a rail
A store has to decide what to accept, find a way to identify it and make it visible to possible buyers. The coat could need checking for hidden wear or a loose fastening and a description that gives its size in a usable form. Staff may put it in a part of the store where people can try it on, make changes agreed under the pricing arrangement and keep it secure. If it goes home with somebody, there is an accounting step for the payment. The visible sale is the end of one relationship and the middle of a different one.
The $33 in the example is a gross share, not profit. Paying people and keeping a place to display clothes can use much of it. A coat that never sells can demand some of the same steps without producing any share at all. A shop may decline items for which it expects few shoppers or a price too small to justify the work. That need not say the garment is unusable or worth nothing to its owner. Perhaps it just needs a different way to find a next wearer. The store is choosing whether to offer its particular service on agreed terms.
For a shop keeping its own records, an item’s days on the rack and its days awaiting a decision are different. Consider a week when twenty coats arrive together and several need another photograph or check before being listed. A snapshot of the number of coats accepted says little about how many were actually ready to sell. The sooner an owner knows which step is delaying them, the sooner they can decide whether to change the selection, schedule or price. Otherwise a large unsold stockpile may be attributed to price when quite a lot of it has never been offered to buyers.
There is a reconciliation after every sale. The date the shop registers one can differ from the date it transfers the money. The agreement should also make clear what happens if an otherwise completed sale can still be returned. A statement showing an amount due and an amount actually paid helps prevent a settlement from being counted twice. That distinction matters to a person whose items leave the same counter several weeks apart.
Ask what information stays with the coat
A concise receipt gives both parties a way to tell which garment the arrangement covers. Use an item identifier and include enough of the description to find it. Put the opening price, treatment of later changes, share and timing of the settlement where someone can read them together. Note what will happen at the end if there is no sale. Private information and payment details should stay with the appropriate records, not on the tag a buyer sees. These are ordinary distinctions, yet a shop that relies on remembering a person by the piece they left can make errors for which neither party is prepared.
A closing comparison can be as simple as two columns. In one, write the price already available from a direct buyer, if there is one. In the other, write two or three plausible outcomes under consignment: sale near the opening tag, sale after a markdown, and no sale during the agreed period. Include what happens to the coat in the last case. Not every person is trying to maximize the same number. Someone may want the space taken up today; another may prefer a chance at a larger payment. The exercise helps because it lets you see what kind of uncertainty each person would be choosing.
When the buyer throws the coat over their shoulders in the store, the tag tells them one thing about that afternoon. They will have reason to know what it costs them. Behind the tag is a second agreement that has run through a different set of days. If the staff can identify the coat and read the price, date and applicable share together, they can finish that agreement with a payment that makes sense to the person who left it, too.